Two buyers with the same budget and the same wish list, a three-bedroom ranch with an updated kitchen, get insurance quotes back on the same afternoon. One home sits in St. Charles County. The other sits in St. Louis County. The quotes land nearly $200 apart before either buyer has negotiated a dollar off the purchase price. Nobody mentioned that on the listing sheet.
That gap is a preview of a bigger one. As of late August 2026, the median sold price across St. Charles County stood at $386,250, up 4.96 percent from a year earlier, on 616 closed sales. St. Louis County's median sold price for the same period was $320,000, up 8.47 percent year over year. Do the math and St. Charles County is commanding roughly a 20 percent premium over its neighbor.
The easy read is that St. Charles County is simply the pricier, more desirable side of the metro. The actual explanation has less to do with desirability and more to do with what year the pipes were installed.
The Gap Is Age, Not Value
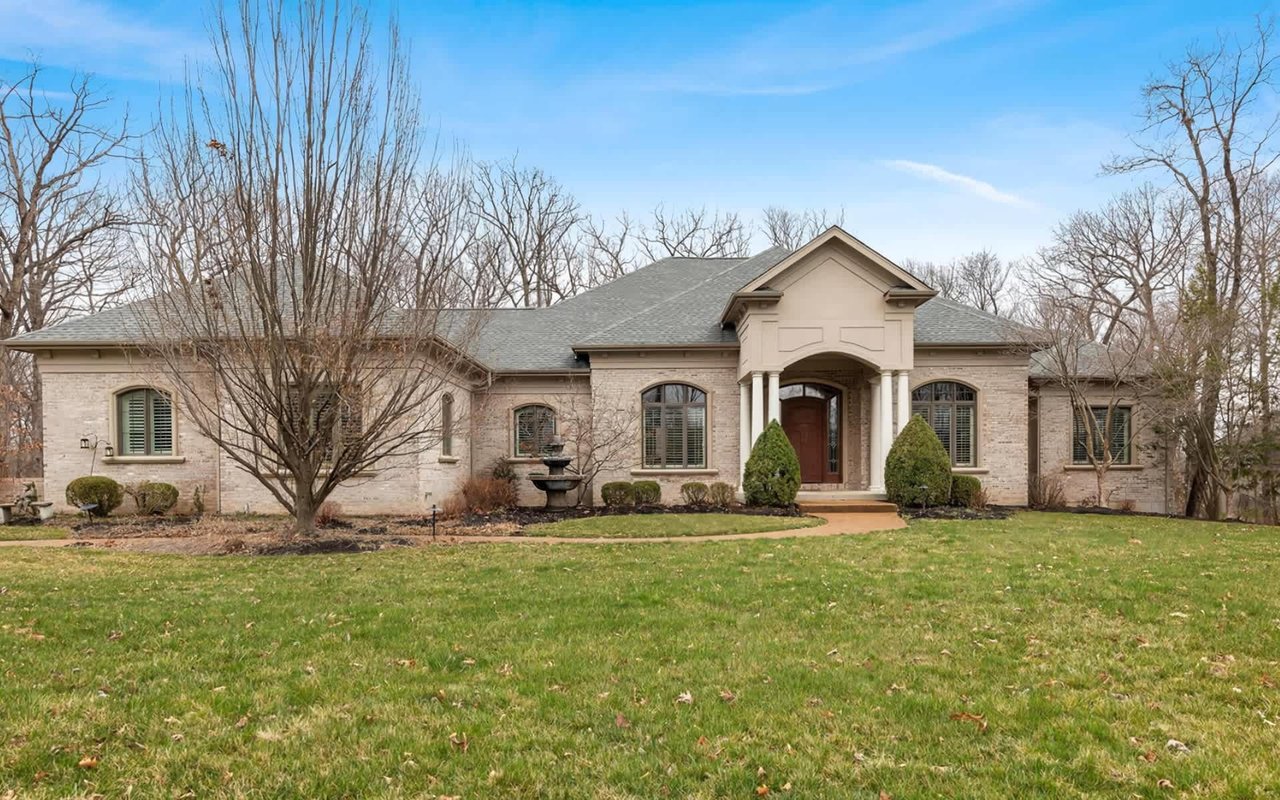
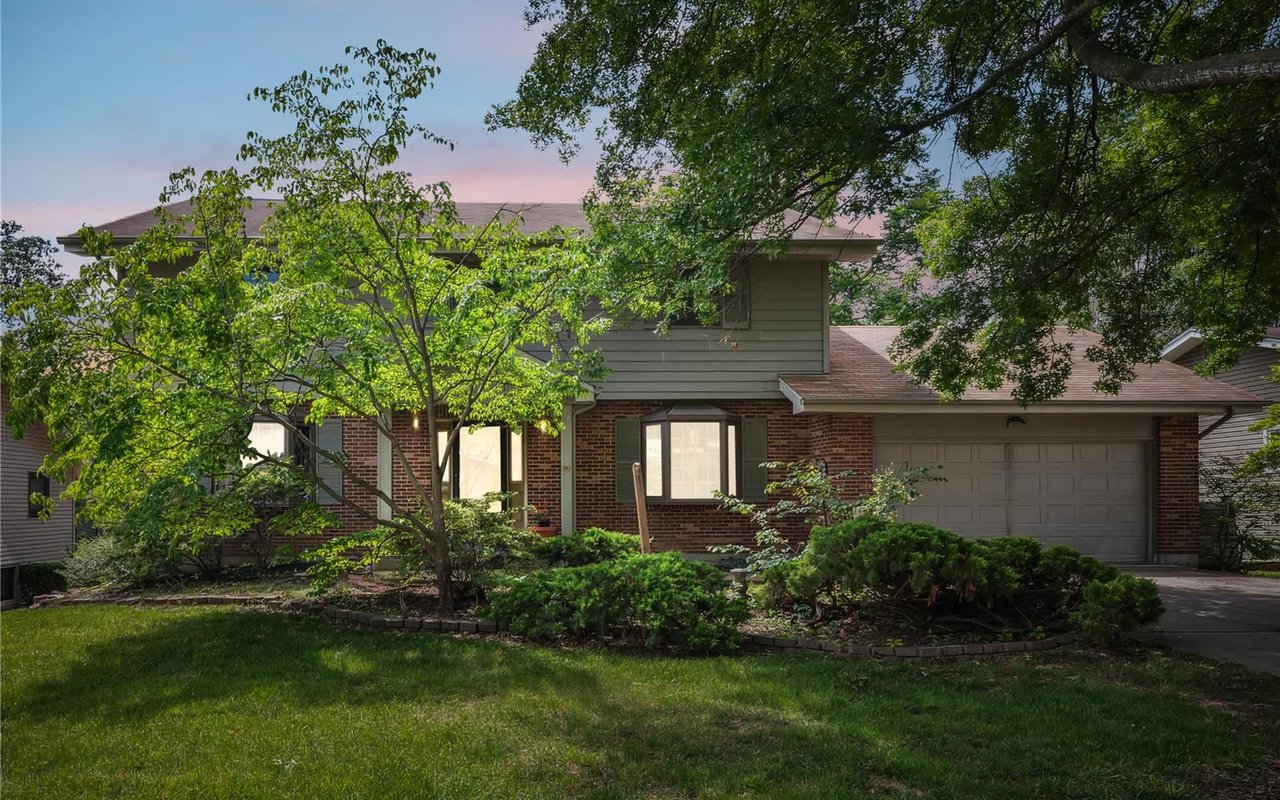
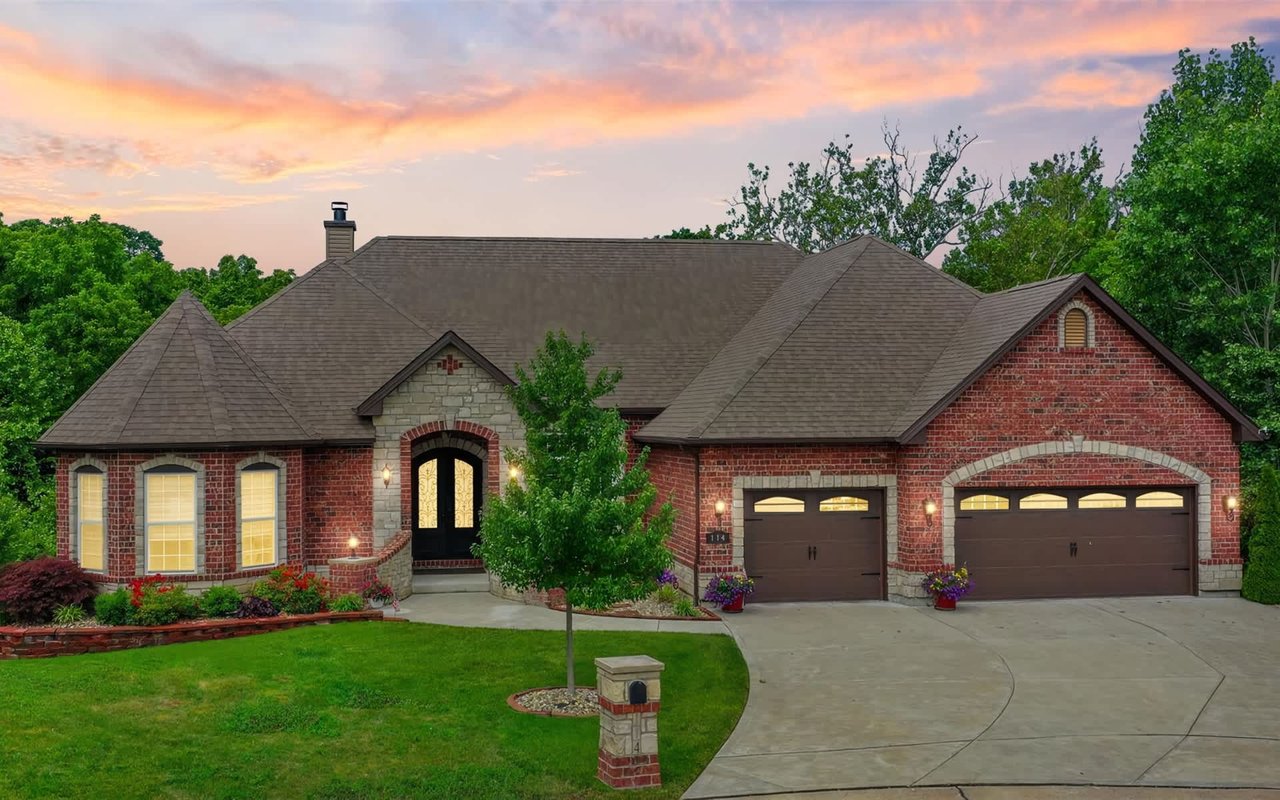
St. Charles County's housing stock is overwhelmingly newer. The county's growth corridors, Wentzville, O'Fallon, and Lake St. Louis among them, have spent the last two decades building post-1990 single-family homes with larger square footage and modern master suites. St. Louis County's inventory tells a different story: a wider mix of condos, attached villas, historic properties, and mid-century ranches sits alongside its newer construction.
That mix changes what the median actually measures. A $386,250 median in St. Charles County isn't pricing a typical house at a premium over an identical St. Louis County house. It's averaging a pool of homes that are, on the whole, younger, bigger, and built to a different code. The 20 percent gap is a stand-in for decades of construction dates, not a verdict on which county is the better buy.
That distinction matters the moment you start comparing two specific listings instead of two headline numbers.
The Insurance Conversation Nobody Has Before Closing
Underwriters price a home by what's inside the walls as much as by its square footage. Homes built before the mid-1970s often carry original cast-iron plumbing stacks, galvanized supply lines, 100-amp electrical panels, and clay sewer laterals, all of which read as risk to an insurer. Homes built to St. Charles County's more recent code typically run PVC plumbing and 200-amp panels, which insure at a lower baseline rate with fewer add-ons required.
The practical consequence for a St. Louis County buyer eyeing an older home: budget for sewer lateral and water backup riders, which commonly run $150 to $300 a year on top of a standard policy. That's not a deal breaker. It's a line item that belongs in your monthly comparison from the start, not something you discover after underwriting flags the panel box during inspection.
If you're the one buying the older home, a few questions are worth asking before you get too attached to a listing:
- When were the plumbing supply lines last replaced, and are they copper, galvanized, or PVC?
- Is the electrical panel rated at 100 amps or 200 amps?
- Has the sewer lateral, the pipe running from the house to the street main, ever been scoped or replaced?
None of these questions are deal killers. They're the difference between a clean insurance quote and one with three riders attached.
Homeowners in St. Charles city itself have a specific resource here that's worth knowing about even if you're buying outside city limits. The city runs a Sewer Lateral Repair Program that reimburses homeowners for up to 90 percent of covered repair costs, capped at $7,500, and the program's rules are laid out directly in the city code. St. Charles County also runs a separate emergency repair program for unincorporated properties tied to the City of St. Charles or St. Peters sewer systems, detailed on the county's own site. Neither program erases the underwriting difference between old and new systems, but they're a real, budgetable backstop if you do end up owning an older lateral.
Why the Premium Isn't Running Away
If St. Charles County commands a genuine premium, you'd expect that gap to widen every year as demand chases limited land. It hasn't, and the reason is supply, not restraint.
Wentzville alone posted 595 home sales in August 2026, up from 427 the year before, even as the area's population keeps climbing toward the metro's fastest-growing corridor. That's not a market running out of houses. It's a market where builders keep delivering finished inventory into subdivisions along the county's western edge, absorbing demand as fast as it shows up. The General Motors assembly plant anchoring that corridor keeps a steady base of buyers wanting to live within a short commute, and the subdivision pipeline keeps pace with them.
That combination, strong demand met by a continuous supply of new construction, is what keeps St. Charles County's price growth in the mid-single digits rather than the double-digit spikes a genuinely supply-starved market would produce. The premium is real. It's also being held in check by the same growth that created it.
The List Price That Didn't Happen
Here's where the numbers get more interesting for anyone shopping right now. In May 2026, St. Charles County's median list price hit $425,000, up 16.44 percent from $365,000 a year earlier. Over that same month, the number of closed sales fell 7.83 percent, to 506 homes, down from 549 in May 2025.
Sellers were asking for more. Fewer buyers were closing at those numbers. By August, the countywide median sold price had settled at $386,250, well under that May list figure. Put those two data points side by side and you get a market where sticker prices climbed faster than buyers' willingness to meet them, which is a different story than the one a single median suggests on its own.
For a buyer, that gap between what sellers ask and what actually closes is where negotiating room lives. A listing priced at or above the spring's asking trend doesn't automatically reflect what the market will bear in September. It reflects what a seller hoped for six months ago.
| St. Charles County | St. Louis County | |
|---|---|---|
| Median sold price (Aug 2026) | $386,250 | $320,000 |
| Year-over-year change | +4.96% | +8.47% |
| Closed sales (Aug 2026) | 616 | — |
| Typical housing stock | Post-1990 single-family | Mixed: condos, villas, mid-century ranches, newer builds |
| Common systems | PVC plumbing, 200-amp panels | Cast-iron, galvanized, 100-amp panels in older homes |
What This Means If You're Choosing Between the Two
Neither county is the objectively better buy. The right one depends on what you're actually optimizing for. If you want a newer home with predictable systems and a straightforward insurance quote, the premium you'll pay in St. Charles County is buying exactly that, and the ongoing new-construction pipeline in Wentzville, O'Fallon, and Lake St. Louis means you'll have real choices at that price point. If you're comfortable budgeting for a lateral inspection and a couple of insurance riders, St. Louis County's older stock can put you in a larger lot or a more established neighborhood for meaningfully less at closing.
What doesn't hold up is treating the median price gap as a simple quality signal. A $66,000 difference in the county-wide median is mostly a reflection of when the homes were built, not how well they were built.
If you're weighing a move across the county line, or trying to figure out what your current home would actually list for in this market, the Cheri Norton Team has spent decades watching these two markets move against each other. Get your free home valuation and we'll walk through what your specific numbers look like, not just the county average.
A Few Questions We Get
Does the higher median price in St. Charles County mean I'd be overpaying compared to St. Louis County? Not necessarily. The gap largely reflects the age and type of housing stock each county's median is built from, not an identical home costing more in one place than the other. Compare specific properties, not county averages, before drawing that conclusion.
If I'm buying an older home in St. Louis County, what should I ask my insurance agent about? Ask about sewer lateral and water backup coverage specifically. Homes with cast-iron plumbing stacks, galvanized supply lines, or 100-amp electrical panels often need riders beyond a standard policy, and knowing the cost upfront keeps your monthly budget accurate.
Is the St. Charles sewer lateral reimbursement program available to buyers of existing homes, or just current owners? The program is tied to the property and its account standing with the city, including current real estate tax payments, rather than to a specific buyer. If you're purchasing a home in St. Charles city limits, it's worth asking the seller or the city directly about the property's account status before you factor the program into your plans.